🚨 Your expensive ergonomic office chair is actively ruining your joints. I spent thousands of dollars trying to buy my way out of chronic lower back stiffness and clicking knees, only to find out that the furniture industry is lying to us. The actual fix to your physical misery is completely free, and it's the exact same mobility strategy used by world-class athletes who squat for a living. The Ergonomic Trap and My $1,200 Mistake For the past four years, my daily routine consisted of waking up, shuffling over to my desk, and sitting for nine to ten hours. About two years ago, the cracks started to show. It began with a dull ache in my lower lumbar spine. Then, my knees started popping like bubble wrap every time I stood up to get a glass of water. Walking down stairs felt like my patellar tendons were being stretched over broken glass. Naturally, I did what any desperate desk worker does: I threw money at the problem. I bought a highly rated ergonomic mesh chair that...
Get link
Facebook
X
Pinterest
Email
Other Apps
I spent years living like a financial daredevil and wiped out my entire net worth. Here is how I was born again from absolute zero.
Get link
Facebook
X
Pinterest
Email
Other Apps
🚨 If you are currently staring at a bank account with double digits, drowning in high-interest debt, or feeling like you completely ruined your life by taking stupid risks—stop scrolling. I was there two years ago. I lost $120,000, my apartment, and my self-respect. Here is how I rebuilt my life from the ashes.
The Daredevil Phase: How I Conned Myself Into Thinking Risk Was Cool
Two years ago, I thought I was invincible. I was the classic "financial daredevil." I had a decent corporate job making around $85k, but instead of doing the boring stuff—like funding a 401k, keeping an emergency fund, or paying off my student loans—I decided I was too smart for traditional personal finance. I wanted the fast track. I wanted the adrenaline rush of high-risk, high-reward plays.
I plunged headfirst into highly leveraged stock options, speculative crypto coins, and lifestyle creep that would make a lottery winner blush. I leased a luxury car I couldn't afford because I believed "you have to look rich to get rich." I put vacations on credit cards, convinced that my next big trade would wipe the balance clean in a single afternoon. Every time a friend warned me about my lack of a safety net, I laughed it off. I told them they had a "scarcity mindset." I was a daredevil, and daredevils don't worry about the safety harness.
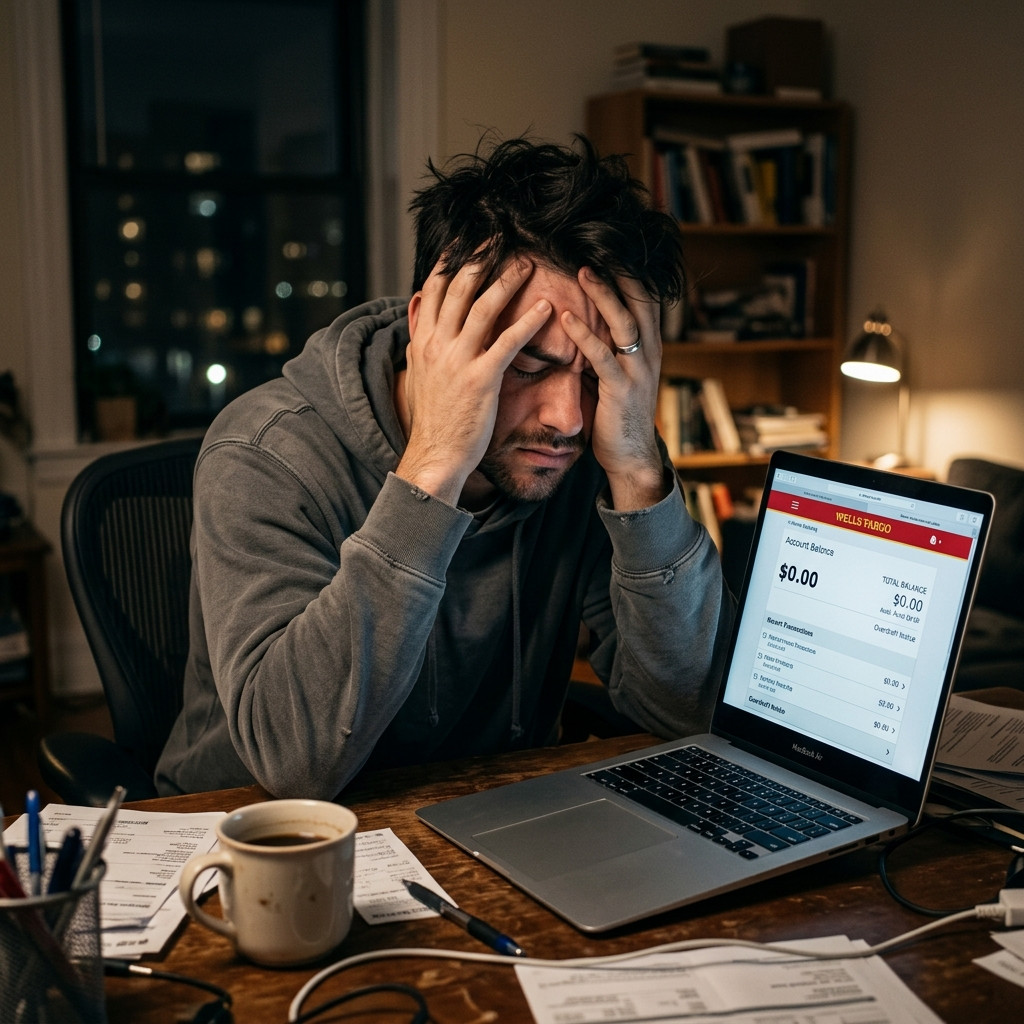
Then, the market turned. My high-risk investments didn't just dip; they evaporated. Within a ninety-day window, my portfolio crashed by 90%, my tech company went through a massive wave of layoffs, and I was handed a pink slip. I had exactly $412 in my checking account, $38,000 in high-interest credit card debt, a $700-a-month car payment, and zero income. I was completely, utterly wiped out. I had to move back into my parents' basement at age 33, feeling like the biggest failure on the planet.
▲ The reality of hitting rock bottom: facing the numbers you ignored for years.
The Day the Floor Fell Out: Surviving the Initial Panic
The first week after hitting rock bottom is a blur of pure, unadulterated panic. When you go from feeling like a financial mastermind to realizing you can't even afford groceries without checking which credit card isn't maxed out yet, your brain goes into survival mode. The shame is paralyzing. You don't want to answer the phone because it's probably a debt collector. You don't want to see your friends because they might ask to grab a beer, and you can't even afford the tax on a draft pint.
But wallowing does not pay the bills. If you find yourself in this exact spot, the first thing you need to do is a hard financial triage. Stop looking at your portfolio. Stop checking the price of whatever asset ruined you. It is gone. Accepting that loss is the hardest, most painful part of being born again financially, but it is non-negotiable. You have to mourn the money, bury it, and move on. Your new job is survival.
Myth-Busting: Why Most 'Financial Advice' is Garbage When You Are Broke
When you start searching for help online, you get bombarded with advice that is completely useless for someone who is actually drowning. Let's bust a few of these common myths right now:
Myth 1: "Just start a side hustle!" Look, when you are suffering from severe financial trauma and panic attacks, telling you to just "work another 30 hours a week driving Uber" is recipe for a physical breakdown. You need mental clarity first, not sleep deprivation. Fix your baseline expenses before you try to work yourself to death.
Myth 2: "Cut out the $5 lattes." If you owe $40,000 to Chase and Citibank, skipping a coffee once a week is like trying to empty the ocean with a teaspoon. It makes you feel miserable and yields almost zero actual progress. Focus on the macro expenses: your car, your rent, and your high-interest debt structure.
Myth 3: "Never settle with debt collectors." Absolute nonsense. When you have no money, debt collectors are your best friends because they are desperate to get *something* rather than *nothing*. I settled a $12,000 credit card bill for $3,500 after six months of aggressive negotiation. It dinged my credit score temporarily, but guess what? You can't buy groceries with a credit score. Cash is king when you are rebuilding.
The Rebirth: How to Set Up Your Triage Budget
To be born again financially, you have to adopt a wartime mindset. Every single dollar that enters your possession must be aggressively weaponized. Here is the exact step-by-step process I used to stabilize my life during those first six months of recovery:
First, I did the most painful thing possible: I sold the luxury car. I took a hit on the loan, but getting rid of that $700 monthly payment plus the insane insurance premium felt like stepping out of a suffocating room. I bought a beat-up, 15-year-old sedan for cash. It was loud, it had a dent on the passenger side, and it smelled slightly like old crayons, but it got me from point A to point B without draining my soul.
Second, I built a zero-based budget. Every single dollar had a name before the month started. If I made $3,000 that month doing freelance writing and odd jobs, every single cent was accounted for. Rent, basic food, utilities, and debt minimums. There was no "miscellaneous" category. If it wasn't on the spreadsheet, it didn't exist.
Rebuilding Your Relationship with Money from Scratch
The hardest part of this journey isn't the math; it's the psychology. When you have lived as a daredevil, boring financial habits feel incredibly slow and frustrating. Saving $50 a week feels pointless when you used to watch your portfolio swing by thousands of dollars a day. You have to completely re-wire your dopamine receptors.
I started gamifying my savings. Instead of chasing massive, risky wins, I found joy in the small, guaranteed victories. Watching my emergency fund grow from $100 to $500, and then to $1,000, gave me a sense of peace that no speculative trade ever did. For the first time in my adult life, I could sleep through the night without checking my phone at 3:00 AM to see how foreign markets were performing.
I also stopped tying my self-worth to my net worth. When you are broke, it is easy to feel like you are a worthless person. But your bank account is just a metric of your past mistakes, not a reflection of your current character. Once I separated my identity from my balance sheet, my mental health skyrocketed, which ironically made me much better at my new job and allowed me to earn more money.
The Rebirth Checklist
Accept the loss: The money you lost is gone. Stop trying to "win it back" with risky plays.
Perform financial triage: Cut the massive expenses first (cars, rent, subscriptions) rather than obsessing over tiny details.
Negotiate everything: Call your creditors, explain your situation honestly, and negotiate lower interest rates or lump-sum settlements.
Re-wire your brain: Find peace in boring, consistent progress. An emergency fund is the ultimate luxury.
"Your chronic fatigue and brain fog aren't a lack of willpower—they're a lack of gut microbes." Welcome to the era of Fibermaxxing. In 2026, Silicon Valley executives and biohackers are dropping extreme diets to focus on the ultimate performance enhancer: The Gut-Brain Axis. 1. The End of the Protein Obsession For years, fitness culture was entirely obsessed with "high protein, low carb." We filled our fridges with chicken breasts and protein powders. But as we move deep into 2026, the paradigm has shifted. High performers are now turning their attention away from protein and toward Fiber . Enter 'Fibermaxxing' . Instead of restricting food groups and inducing metabolic stress, people are dramatically increasing their intake of complex, high-quality fibers—like lentils, beans, and whole grains—to reduce systemic inflammation and unlock ...
The 2026 Wellness Shift: Why 'Sleep Recovery' is the Ultimate Weight Loss Hack "I am eating less and working out endlessly, but the scale won't budge." This is the universal frustration of chronic dieters. However, as we move through 2026, the global wellness industry and viral TikTok trends have abruptly shifted focus away from high-intensity workouts and extreme caloric deficits. Today, top fitness experts and Silicon Valley biohackers are obsessed with one metric above all else: Data-Driven Sleep Recovery . When you are sleep-deprived, your body enters a state of primal emergency, aggressively storing fat around your midsection. Conversely, when you optimize your sleep architecture, your body becomes an ultra-efficient fat-burning furnace overnight. In this deep dive, we explore the trending science behind the sleep-optimization diet and provide actionable protocols you can implement tonight to transform your metabolism. Photo: Cultivatin...
🌙 When was the last time you woke up actually feeling rested? Let’s be honest. Surviving the morning on three cups of coffee and doom-scrolling until 2 AM despite being exhausted has become the norm for too many of us. But in 2026, the global elite and high-performing Millennials are flipping the script. They aren't boasting about running on 3 hours of sleep anymore. Instead, they are obsessing over 'Sleepmaxxing' —the art of using cutting-edge Sleep Tech to hack their biology and achieve the most brutally efficient, restorative deep sleep possible. 1. Quality Over Quantity: The Era of 'Amplified Efficiency' It's no longer just about sleeping for 8 hours; it's about how you sleep. The 2026 sleep industry is dominated by the concept of 'Amplified Efficiency.' High-achievers are aiming to get the restorative equivalent of 10 hours of sleep in just 6 hours. How? Through active intervention. AI-pow...



Comments
Post a Comment